

Why Is Aave Pushing Deeper Into Tokenized Assets?
Aave is expanding its lending infrastructure toward tokenized real-world assets as founder and CEO Stani Kulechov argues that institutional demand could become one of decentralized finance’s largest sources of borrowing activity.
The protocol is preparing a dedicated real-world asset lending hub on Avalanche that would allow institutions to use eligible tokenized financial assets as collateral for stablecoin loans. The model is designed to let borrowers obtain liquidity without selling the underlying assets.
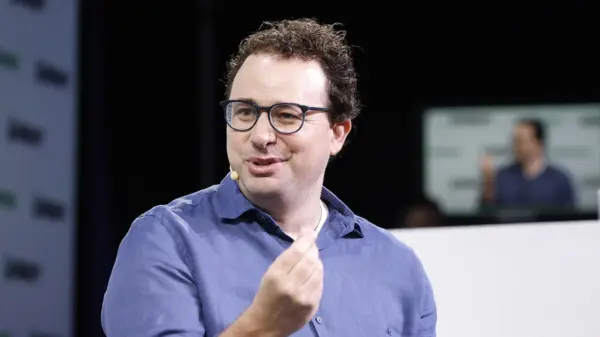
“Institutions come with size, so that’s where a lot of the demand will come,” Kulechov said during Avalanche Summit in New York.
The strategy extends Aave beyond the crypto-native collateral that has historically powered DeFi lending. Tokenized stocks, securities and other financial assets could create a much larger collateral base if institutional issuers and investors begin using public blockchain infrastructure for financing rather than only issuance and settlement.
Aave V4 already went live on Avalanche in July with a hub-and-spoke architecture that allows different lending markets to share liquidity while separating their individual risk profiles. A dedicated RWA market was identified as a later stage of that rollout.
Aave Labs has also proposed an isolated V4 hub and spoke that would allow institutionally custodied assets to support stablecoin borrowing. Under that design, collateral would remain with a custodian while an onchain representation could be used within Aave, connecting traditional custody arrangements with DeFi lending infrastructure.
Why Does Institutional Borrowing Matter for Aave?
Tokenization has so far concentrated heavily on putting assets onchain. Aave is targeting the next step: making those assets productive collateral.
An institution holding tokenized securities could potentially borrow stablecoins against those positions instead of selling them to raise cash. That creates borrowing demand for Aave while giving tokenized assets another financial use beyond ownership and transfer.
Kulechov argues that the technical barriers are no longer the main obstacle.
“Tokenization and DeFi are not a technological challenge anymore,” he said. “I think it’s a go-to-market challenge.”
That distinction matters for the economics of tokenized assets. Issuing a fund, security or other financial instrument onchain does not by itself create deep secondary markets or financing demand. Lending markets, collateral infrastructure and stablecoin liquidity can make those assets more useful once they have been issued.
Investor Takeaway
Aave’s RWA strategy is increasingly about turning tokenized assets into collateral rather than simply supporting their issuance. If institutions begin borrowing against large tokenized portfolios, the result could expand both stablecoin demand and Aave’s addressable lending market.
What Does Kulechov Mean by an “Uber Path” to Regulation?
Kulechov is also arguing that DeFi adoption itself could influence how regulators eventually approach the sector.
He described a potential “Uber path” in which decentralized financial services grow sufficiently useful and widely adopted that policymakers ultimately have to establish workable rules around them rather than waiting for regulation to arrive before expansion.
“But if that doesn’t obviously happen, I think the ultimate goal is to really use this technology and empower millions of people around the world,” Kulechov said when discussing the possibility that U.S. digital asset legislation remains delayed.
“So that’s why I call it the Uber path in the future,” he added.
The strategy carries a practical implication for Aave. Rather than relying exclusively on regulatory developments to unlock institutional growth, the protocol is building infrastructure that could make tokenized collateral and onchain borrowing commercially useful first.
Can Aave Reach Institutions and Retail Users at the Same Time?
Aave’s expansion is not limited to institutional credit. The company is also developing a consumer-facing application intended to make DeFi savings resemble a conventional financial product.
Kulechov said the app is designed to hide much of the technical complexity associated with crypto, including wallets, blockchain networks and individual stablecoins. Users would instead be able to move money between bank accounts and Aave through a simpler interface.
That creates two separate growth routes. Institutional infrastructure could bring larger collateral positions and borrowing volumes into Aave, while the consumer product could broaden access beyond experienced DeFi users.
“I think DeFi will be plugging all finance in the next couple of decades,” Kulechov said.
For Aave, the near-term test is whether tokenization can move from asset issuance into sustained borrowing demand. Institutions may provide the size Kulechov expects, but the RWA market will need sufficient collateral, stablecoin liquidity and operational integration before tokenized finance becomes a material part of Aave’s lending business.